
TL;DR:
- Understanding the unique wildfire risks and market fluctuations in Sonoma County is crucial for obtaining proper insurance coverage.
- Local insurance agents offer invaluable expertise, including policy interpretation, claim advocacy, and relationships with regional adjusters.
- Choosing an independent agent provides greater flexibility and market options, essential for navigating carrier withdrawals and rising premiums in this high-risk region.
Not all insurance is created equal, and understanding why local insurance matters could be the difference between a smooth claims process and a costly dispute. Sonoma County homeowners and business owners face risks that simply don’t exist in most other parts of California. Wildfire exposure, storm damage, shifting carrier availability, and rising premiums create a genuinely complex environment. The idea that insurance works the same everywhere is one of the most expensive misconceptions you can hold. Your coverage, your claims, and your outcomes all depend heavily on local knowledge.
Table of Contents
- Understanding the unique insurance challenges in Sonoma County
- How local knowledge makes a real difference in insurance claims and coverage
- Comparing independent and captive local insurance agents: which fits Sonoma County needs?
- Practical tips for Sonoma County homeowners and business owners to optimize local insurance protection
- Decoding claims strategies: avoiding common pitfalls with local insurance expertise
- Why trusting local expertise is your smartest insurance strategy in Sonoma County
- Protect your Sonoma property with trusted local insurance experts
- Frequently asked questions
Understanding the unique insurance challenges in Sonoma County
Sonoma County sits in a region where the insurance landscape changes faster than almost anywhere in the state. Wildfire risk has pushed carriers to reduce coverage, raise prices, or leave the market entirely. When storms roll through, damage claims spike, and homeowners often find themselves unprepared for what the process actually involves.
Here are some of the core challenges local property owners face right now:
- Wildfire exposure continues to drive underwriting decisions, making some properties harder to insure at any reasonable price.
- Storm damage claims require prompt action. Insurers must notify policyholders within 40 days whether a claim is covered, with possible extensions depending on complexity.
- Documentation requirements are stricter than most people expect. Photos, written damage assessments, and contractor estimates all factor into outcomes.
- Carrier withdrawal from high-risk zones leaves many homeowners with limited options outside the California FAIR Plan.
- Premium escalation is not just a rumor. The FAIR Plan, which serves as a last resort for homeowners who can’t find standard coverage, has requested an average statewide rate increase of over 35% driven by wildfire risks and claims.
What this means for you: The FAIR Plan offers narrow, expensive coverage with none of the flexibility of a standard policy. It should be viewed as a safety net, not a permanent solution. If you’re on it, local expertise can help you find a better path.
Working with someone who understands these wildfire insurance challenges specific to this region is not optional anymore. The importance of local insurance shows up immediately when you try to navigate these pressures without guidance.
How local knowledge makes a real difference in insurance claims and coverage
The advantages of local insurance agencies go well beyond having a phone number to call. A local agent who knows Sonoma County works inside a web of relationships and regional knowledge that directly improves your coverage and claims experience.
Here’s exactly how that plays out in practice:
- Policy interpretation. A local agent helps interpret policies, assist with filings, follow up with adjusters, and provides real claims advocacy when disputes arise.
- Claim timing guidance. Not every piece of damage is worth claiming. If repair cost is not higher than your deductible, filing may cost you more in future premiums than you recover.
- Local adjuster relationships. Local agents often know the adjusters working in your area. That familiarity speeds communication and reduces back-and-forth delays.
- Building code awareness. Sonoma County has specific local ordinances that affect reconstruction requirements. Your agent should know these and ensure your policy accounts for them.
- Seasonal risk knowledge. Whether it’s fire season preparation in summer or storm drainage issues in winter, local agents factor in the rhythms of this specific region.
Pro Tip: Before storm season begins, ask your agent to walk through your current policy and identify any gaps related to local risks. That conversation takes 20 minutes and can prevent a very unpleasant surprise during a claim.
The benefits of a local insurance agent are clearest when something goes wrong. A national call center reads from a script. A local agent picks up the phone knowing your name, your property, and your history.
Comparing independent and captive local insurance agents: which fits Sonoma County needs?
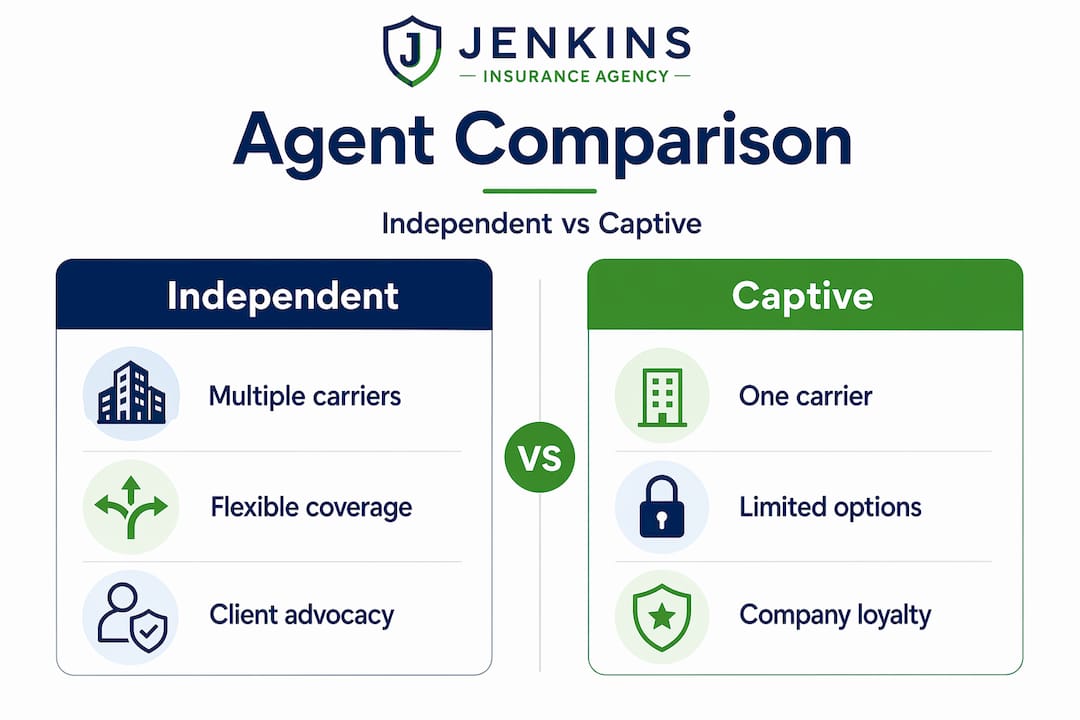
Not every local agent operates the same way. Understanding the difference between independent and captive agents is especially important in Sonoma County, where carrier flexibility can directly affect your ability to stay insured at a reasonable price.
| Feature | Independent agent | Captive agent |
|---|---|---|
| Carriers represented | Multiple carriers (15 to 30+) | Single carrier |
| Market flexibility | High | Low |
| Price comparison | Yes, across multiple options | Limited to one company |
| Response to carrier withdrawals | Can pivot to new carriers | Locked into one company’s decisions |
| Personalized coverage matching | Broader options available | Limited by one carrier’s products |
In a market like Sonoma County, where carriers regularly change their appetite for wildfire-exposed properties, the ability to shop multiple carriers is genuinely valuable. If your current carrier raises rates significantly or exits the market, an independent agent can move your coverage quickly without starting your relationship from scratch.
Key reasons independent agents often serve Sonoma clients better:
- They can find coverage when one carrier says no.
- They compare pricing across the market, not just within one company’s rate structure.
- Their loyalty is to you, not to a carrier’s sales targets.
- They have a broader view of what’s available at any given moment in the California market.
Pro Tip: Ask any agent you’re considering how many carriers they represent and when they last moved a client to a different carrier due to pricing or availability. The answer tells you a lot about how they actually work.
Exploring independent insurance agencies advantages in detail is worth your time before you commit to any agent relationship.
Practical tips for Sonoma County homeowners and business owners to optimize local insurance protection
Knowing why local insurance matters is the first step. Using that knowledge actively is what protects you when it counts. Here’s what we recommend doing right now:
- Take annual property photos. Walk through every room and around the exterior of your property once a year. Detailed photos and records aid significantly in claim documentation and insurer valuation.
- File claims promptly. The clock matters. Delays in reporting damage can create complications with coverage determinations.
- Know your deductible before damage happens. This prevents emotional decision-making after a loss.
- Invest in mitigation, but with realistic expectations. Brush clearing and home hardening help, but mitigation efforts do not always guarantee lower premiums, which is why tailored local guidance remains essential.
- Review your policy every year. Coverage needs shift. Renovations, new equipment, business changes, and updated replacement costs all need to be reflected in your policy.
Pro Tip: Store your annual property photos in a cloud account, not just on your phone. After a wildfire or major storm, local devices can be lost or damaged at the exact moment you need those records most.
A home insurance checklist for Sonoma County can help you stay on top of these steps without letting anything fall through.
Decoding claims strategies: avoiding common pitfalls with local insurance expertise
Claims are where the real value of local insurance expertise shows up, and also where the most costly mistakes happen. Here’s what trips up Sonoma County property owners most often.
What your policy may not cover:
- Flood damage is commonly misunderstood. Insurers differentiate damage causes such as rain and wind versus flooding, which directly affects claim eligibility. Flood typically requires separate coverage.
- Gradual wear and maintenance issues are rarely covered under any standard policy.
- Some policies exclude specific perils that are common in this region. You need to know what’s on that list before something happens.
Pro Tip: Read your “exclusions” section once a year. Most homeowners never do. It’s three pages that can save you from a very unpleasant surprise.
The financial logic of filing:
Only file a claim if repair cost exceeds your deductible to avoid unnecessary premium impacts and lost time. Filing a $900 claim with a $1,000 deductible accomplishes nothing except a claims record that could affect your rates.
What local agents do better than any app:
A local agent walks you through whether to file before you file. That conversation, which takes minutes, can prevent premium increases and protect your claims history. It also surfaces insurance claims explained in California in plain language, not policy-speak.
The impact of local insurance expertise is most visible in moments like these. You get guidance tailored to your situation, not a generic FAQ.
Why trusting local expertise is your smartest insurance strategy in Sonoma County
Here’s something most insurance articles won’t say directly: insurance is not a commodity. Treating it like one is exactly how people end up underinsured, denied on claims, and stuck on the FAIR Plan.
We’ve seen what happens when homeowners pick coverage based purely on price from a national online platform. They often don’t discover the gaps until a wildfire burns through or a storm floods their crawl space. By then, the savings they celebrated look very different.
Insurance is a relationship. Local agents’ reputational capital with adjusters, contractors, and local officials genuinely accelerates claims and can uncover coverage that a policyholder didn’t even know they had. That relationship isn’t built on one transaction. It’s built over years.
The local insurance advantages we’re talking about aren’t about charm or convenience. They’re about outcomes. Local agents adapt to market shifts faster because they’re watching those shifts in real time, in the same community you live in. When a carrier changes its wildfire underwriting overnight, a local agent who knows your property can respond before you even hear the news.
Long-term agent relationships also produce better results in ambiguous claim situations. An adjuster who hears from an agent they know and trust handles that file differently than one who gets a cold call from a stranger. That’s not a theory. That’s how it works.
If you’ve been treating insurance as a once-a-year transaction to be handled as quickly as possible, we’d encourage you to think about local insurance agencies matter in Sonoma differently. The relationship you build now is the asset you’ll rely on when you need it most.
Protect your Sonoma property with trusted local insurance experts
At Jenkins Insurance Agency, we work with homeowners and business owners throughout Sonoma County who want more than a policy number. We understand the local risks, the carrier landscape, and what it actually takes to protect your property in this specific region.

Whether you need Sonoma homeowners insurance that accounts for wildfire exposure or Sonoma business insurance that keeps your operations covered through market changes, we’re here to guide you. We help you understand your coverage, make smart claims decisions, and adapt your protection as your needs evolve. Choosing a local insurance agent who knows this community is one of the most practical steps you can take to secure real peace of mind.
Frequently asked questions
Why should I choose a local insurance agent in Sonoma County?
Local agents understand Sonoma County’s unique risks, regulations, and claims processes, delivering faster, clearer outcomes when something goes wrong and providing personalized guidance that a national platform simply cannot match.
When is it financially beneficial to file an insurance claim for property damage?
It’s generally worth filing only when repair costs exceed your deductible. As confirmed by local claims guidance, filing below your deductible threshold adds a claims record without any financial benefit.
How do wildfire risks affect insurance availability and premiums in Sonoma County?
Wildfire exposure has pushed carriers out of the market and driven up costs significantly, with the FAIR Plan requesting an average increase over 35% statewide, leaving many homeowners with limited and expensive options.
What’s the difference between independent and captive local insurance agents?
Independent agents represent 15 to 30 or more carriers and can compare options across the market, while captive agents work with one carrier only, which limits flexibility especially when market conditions shift quickly.
How can I prepare for the claims process after storm or wildfire damage?
Document damage immediately with thorough photos and written records, file promptly, and lean on your local agent to coordinate with adjusters. Filing right away with detailed records significantly improves the speed and fairness of your settlement.
Recommended
- Wildfire Insurance: What Every Sonoma County Homeowner Should Know – Jenkins Insurance Agency Inc.
- Business Insurance Benefits for Sonoma County Owners – Jenkins Insurance Agency Inc.
- The Best Small Business Insurance Plans in Sonoma County – Jenkins Insurance Agency Inc.
- Home Insurance Checklist: Sonoma County Homeowners’ Guide – Jenkins Insurance Agency Inc.