
TL;DR:
- Insurance in Sonoma County is vital for protecting property and financial stability against wildfire, liability, and economic disruptions. Due to increasing wildfire risk and insurer behavior changes, residents should proactively document mitigation efforts and verify coverage before purchasing or renewing policies. Proper insurance management enhances property value, community resilience, and personal financial security in this high-risk region.
Insurance in Sonoma County is defined as a financial risk management tool that protects your home, vehicle, business, and personal wellbeing against losses driven by wildfire, liability, and economic disruption. Knowing why get insured in Sonoma County matters more here than almost anywhere else in California. The region’s fire history, shifting insurer behavior, and state regulations have made coverage decisions far more complex than simply picking a price. Whether you own a home in Santa Rosa, run a business in Petaluma, or are buying your first property in Healdsburg, the right insurance policy is the difference between recovery and financial ruin.
Why wildfire risk makes getting insured in Sonoma County urgent
Sonoma County sits in one of the most fire-prone regions in the United States. The 2017 Tubbs Fire and 2019 Kincade Fire destroyed thousands of structures and reshaped how insurers assess risk here. The result is an insurance market under serious pressure, and residents feel it directly in their premiums and coverage options.
Sonoma County’s median annual premium reached $1,834 in 2024, nearly a 40% increase over a decade. That number reflects the compounding effect of wildfire losses on insurer profitability, and it signals that costs will continue rising without meaningful mitigation. For many residents, this premium spike has pushed coverage from a routine expense into a genuine financial planning challenge.
Insurers no longer rely solely on official fire hazard maps to make underwriting decisions. They assess roof materials, defensible space, proximity to vegetation, and local fire department response times. A home in a moderate-risk zone on paper may still face coverage denial if the physical property does not meet underwriting standards. This means two neighbors on the same street can receive very different offers.
| Scenario | Likely outcome |
|---|---|
| Home with Class A roof, cleared defensible space | Standard-market coverage available, competitive premiums |
| Home with wood shake roof, dense vegetation nearby | Possible denial or placement in California FAIR Plan |
| Home with partial mitigation, no documentation | Discount eligibility lost, higher premiums |
| Home with full mitigation and inspection reports | Up to 14.6% discount on wildfire premium portions |
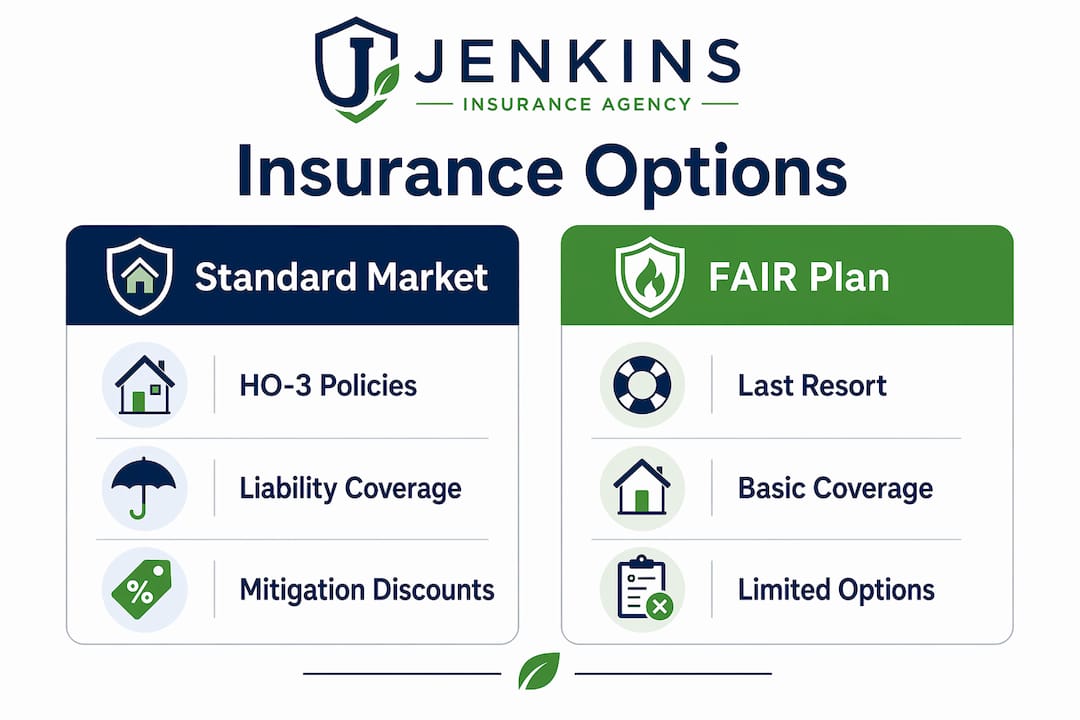
When standard-market insurers decline coverage, the California FAIR Plan steps in as the insurer of last resort. The FAIR Plan covers named perils like fire but excludes liability, theft, water damage, and personal property. Most homeowners on the FAIR Plan need a supplemental difference-in-conditions policy to fill those gaps, which adds cost and administrative complexity.
Pro Tip: If you are shopping for a home in Sonoma County, confirm insurance availability before making an offer. Discovering that a property is uninsurable or FAIR Plan-only after signing a purchase agreement can delay or kill the transaction entirely.
How insurance protects your property value and financial security
Fire insurance has become the biggest predictor of a homeowner’s ability to rebuild after a wildfire, making coverage central to housing stability and community resilience across Sonoma County. This is not just about replacing a structure. It is about maintaining the financial foundation that your home represents.
The benefits of being insured in Sonoma extend directly into real estate market dynamics. Homes with accessible, affordable insurance attract larger buyer pools and stronger offers. Homes that are difficult to insure face narrower buyer pools, longer days on market, and reduced negotiating leverage for sellers. Insurability now shapes market value in ways that appraisals do not fully capture.
California’s AB 38 requires sellers in high fire-risk areas to disclose whether they have completed defensible space inspections and home hardening measures. This law connects mitigation directly to insurance eligibility and transaction transparency. Buyers who see documented mitigation work gain confidence in both the property and its insurability, which translates into real dollars at the negotiating table.
Here is what insurance coverage in Sonoma protects beyond the structure itself:
- Mortgage eligibility. Lenders require homeowners insurance as a condition of most mortgages. Without it, financing falls apart.
- Liability protection. A guest injured on your property, or a fire that spreads to a neighbor’s home, can generate six-figure legal claims without liability coverage.
- Business continuity. A wildfire that forces your business to close for weeks can be survivable with business interruption insurance and unrecoverable without it.
- Personal financial resilience. Life and health insurance protect your family’s income and medical costs, keeping a personal disaster from becoming a generational one.
What insurance options in Sonoma County are available to you
Sonoma County residents typically need coverage across four categories: homeowners, auto, business, and personal insurance. Each carries region-specific considerations that generic online policies often miss.
Homeowners insurance
Homeowners insurance types range from HO-3 open-peril policies to HO-8 policies designed for older homes. In Sonoma County, the key distinction is whether a policy covers wildfire as a named peril and whether the replacement cost coverage is sufficient given local construction costs. Post-wildfire rebuilding in the North Bay has driven construction costs well above pre-fire appraisals, making guaranteed replacement cost endorsements worth the added premium.
Auto insurance
California law requires minimum liability coverage of $15,000 per person and $30,000 per accident for bodily injury, plus $5,000 for property damage. These minimums are low relative to actual accident costs in 2026. Auto insurance coverages like uninsured motorist protection and comprehensive coverage matter especially in Sonoma County, where rural roads, deer crossings, and wildfire evacuation traffic create elevated accident risks.
Business insurance
Sonoma County’s economy includes wineries, hospitality businesses, contractors, and retail shops, each with distinct liability and property exposures. General liability, commercial property, and business interruption coverage form the core of most business policies. Workers’ compensation is mandatory in California for any business with employees. For more on protecting your business locally, the risks specific to Sonoma County are worth reviewing in detail.
Personal insurance
Life and health insurance protect the people behind the property. A term life policy through a carrier like Farmers Insurance can replace income for a family if a primary earner dies, preventing a financial crisis from compounding a personal one. Health insurance reduces the risk that a medical event drains the savings you have built to protect everything else.
Bundling homeowners and auto policies with a single carrier typically generates discounts of 10% to 25%. Local agents who know Sonoma County’s risk profile can identify bundling opportunities and coverage gaps that online comparison tools miss.
How to reduce insurance costs and keep your coverage in Sonoma County
Managing insurance costs in Sonoma County requires a combination of physical upgrades, documentation discipline, and smart shopping. The good news is that California has created real financial incentives for residents who take mitigation seriously.
-
Complete documented wildfire mitigation. California’s Safer from Wildfires program requires admitted insurers to offer premium discounts for documented mitigation measures. Eligible homeowners can receive up to 14.6% off the wildfire-related portions of their premiums. Qualifying measures include defensible space clearance, ember-resistant vents, Class A roofing, and participation in recognized fire safety programs.
-
Keep your documentation current. Mitigation documentation must align with regulatory checklists. Inspection reports, contractor receipts, and program participation certificates are all required. Missing paperwork means missing discounts, even if the physical work is complete.
-
Shop before renewal, not after. The insurance market in Sonoma County changes faster than most residents realize. Comparing quotes from multiple admitted carriers and the FAIR Plan at least 60 days before renewal gives you time to act on better options.
-
Consider a higher deductible. Raising your deductible from $1,000 to $2,500 can meaningfully reduce annual premiums. This works best when you have an emergency fund to cover the deductible if a claim arises.
-
Assess insurability before buying. Confirming insurance availability before making an offer on a Sonoma County property is now a front-line due diligence step, not an afterthought. Microclimate, vegetation density, and prior claims history all affect what coverage is available and at what cost.
-
Work with a local agent. A local agent familiar with Sonoma County’s specific risk zones can identify carriers still writing policies in your area, flag discount programs you qualify for, and help you avoid coverage gaps that generic online policies leave open.
Pro Tip: Ask your agent specifically about the Safer from Wildfires checklist before your next renewal. Many homeowners have completed qualifying mitigation work but never submitted the documentation, leaving real savings unclaimed.
Key takeaways
Getting insured in Sonoma County protects your home, finances, and community resilience against wildfire risk, liability, and market disruption that no other region in California faces at the same scale.
| Point | Details |
|---|---|
| Wildfire drives premium increases | Sonoma County’s median home insurance premium rose nearly 40% over a decade, reaching $1,834 in 2024. |
| Insurability affects property value | Homes with accessible coverage attract stronger offers and larger buyer pools in fire-prone areas. |
| FAIR Plan has real limits | The California FAIR Plan excludes liability, theft, and water damage, requiring supplemental policies for full protection. |
| Mitigation discounts are real | Documented wildfire mitigation can reduce wildfire-related premium portions by up to 14.6% under state regulations. |
| Early diligence prevents surprises | Confirming insurance availability before a home purchase or policy renewal prevents costly delays and coverage gaps. |
What I’ve learned from watching Sonoma County’s insurance market change
I have watched the insurance conversation in Sonoma County shift dramatically over the past several years. What used to be a routine checkbox at closing has become one of the most consequential decisions a homeowner or buyer makes. The residents who navigate this market well share one trait: they treat insurance as a planning tool, not a reaction to a crisis.
The wildfire threat is not going away. What changes is how prepared you are when it arrives. Homeowners who invest in defensible space and home hardening, document everything carefully, and work with a local agent who knows the market are consistently better positioned. They qualify for discounts, retain standard-market coverage, and recover faster when losses occur.
The other thing I have seen is how much the insurance decision affects everything downstream. A property that cannot be insured affordably is harder to sell, harder to finance, and harder to rebuild after a loss. That is not a hypothetical. It is what happened to thousands of Sonoma County families after the Tubbs and Kincade fires. The residents who had adequate coverage rebuilt. Many who did not are still dealing with the consequences.
My honest advice: do not wait for a renewal notice or a real estate transaction to think about your coverage. Review your policy now, check your mitigation documentation, and talk to someone who knows this market. The wildfire insurance considerations specific to Sonoma County are detailed enough that a local agent’s guidance is worth far more than any online comparison tool.
— Jason
Get personalized insurance coverage for your Sonoma County situation
Living and working in Sonoma County means facing risks that require more than a generic policy. Jenkins Insurance Agency Inc. is a local agency based in Santa Rosa, affiliated with Farmers Insurance, and focused on building real relationships with the people and businesses we serve throughout the county.

We help homeowners, drivers, business owners, and families find coverage that fits their unique situation, not just the cheapest option available. Whether you need homeowners insurance built around wildfire risk, auto insurance that meets California’s requirements, business coverage for your local operation, or life insurance to protect your family’s future, we are here to walk you through every option. Reach out to our local team and get coverage that actually works for where you live.
FAQ
Why is insurance so expensive in Sonoma County?
Sonoma County’s home insurance premiums have risen nearly 40% over a decade, driven by wildfire losses that have made the region one of the highest-risk markets in California. Insurers price policies to reflect the probability and cost of claims, and Sonoma County’s fire history pushes both figures higher.
What is the California FAIR Plan and do I need it?
The California FAIR Plan is the state’s insurer of last resort for property owners who cannot obtain standard-market coverage. It covers named perils like fire but excludes liability, theft, and water damage, so most FAIR Plan policyholders also need a supplemental difference-in-conditions policy.
Can I get a discount on my home insurance for wildfire mitigation?
Yes. California’s Safer from Wildfires regulation requires admitted insurers to offer documented mitigation discounts of up to 14.6% on wildfire-related premium portions. You must submit inspection reports and receipts to qualify, so documentation is as important as the physical work itself.
How does insurance affect buying or selling a home in Sonoma County?
Insurance availability directly affects buyer pools, financing options, and negotiating leverage in Sonoma County real estate. Homes that are difficult or expensive to insure attract fewer buyers and weaker offers, making insurability a material factor in property value.
When should I check on my insurance coverage?
Check your coverage at least 60 days before renewal and before making any real estate offer in Sonoma County. Early insurance diligence prevents transaction delays, coverage gaps, and missed discount opportunities that are difficult to recover once a policy period has started.
Recommended
- Home Insurance Checklist: Sonoma County Homeowners’ Guide – Jenkins Insurance Agency Inc.
- Why Insure Your Business: Protecting Sonoma County Owners – Jenkins Insurance Agency Inc.
- Wildfire Insurance: What Every Sonoma County Homeowner Should Know – Jenkins Insurance Agency Inc.
- Why local insurance matters for Sonoma County owners – Jenkins Insurance Agency Inc.