
Every family in Sonoma County faces tough financial questions when planning for the future, especially when considering how to protect loved ones if the unexpected happens. Many people wrongly assume employer-provided life insurance is enough, yet research shows that relying only on workplace coverage often leaves gaps that can create serious hardships for dependents. This article lays out the basics of life insurance, explains what a death benefit covers, and clears up common misconceptions so you can make informed decisions and safeguard your family’s financial security.
Table of Contents
- What Life Insurance Is And Common Misconceptions
- Types Of Life Insurance Policies Explained
- How Life Insurance Secures Your Family
- Local Benefits For Sonoma County Residents
- Financial Implications And Choosing The Right Policy
Key Takeaways
| Point | Details |
|---|---|
| Understand Coverage Needs | Determine your family’s specific financial obligations to assess adequate life insurance coverage. |
| Address Common Misconceptions | Many overestimate costs and believe employer coverage is sufficient, leading to potential financial gaps. |
| Choose the Right Policy Type | Evaluate whether term or permanent life insurance aligns with your financial goals and budget. |
| Seek Professional Guidance | Consult with local agents to tailor coverage to your unique situation and ensure proper protection. |
What Life Insurance Is and Common Misconceptions
Life insurance is straightforward: you pay regular premiums, and when you pass away, the policy pays a death benefit to your loved ones. That’s the core promise. But many people in Sonoma County don’t fully understand what this means for their families or how it actually works.
The real value lies in what that money does. Life insurance provides cash to family members after the insured’s death, replacing lost income and covering immediate expenses like funeral costs, ongoing housing and health care needs, and future goals like college tuition. Think of it as your financial voice speaking for your family after you’re gone.
What Life Insurance Actually Covers
Your death benefit can address multiple financial pressures your family might face:
- Funeral and burial expenses (typically $7,000-$12,000 in California)
- Mortgage or rent payments so your family doesn’t lose the home
- Medical and nursing care costs already incurred
- Outstanding debts like credit cards or car loans
- Child care expenses while surviving spouses work
- Education costs for your children’s future
- Living expenses while your family adjusts to single income
When you die, the insurance company doesn’t negotiate or delay—they pay the benefit to your designated beneficiaries. That’s the promise kept.
Common Misconceptions That Hold People Back
Misunderstandings about life insurance keep many Sonoma families unprotected. Here are the ones we hear most often:
“I don’t need it because my employer provides coverage.” Employer plans are helpful, but they’re rarely enough. Most employer policies replace only 1-2 times your salary, when financial experts recommend 5-10 times. Plus, if you leave that job, your coverage disappears. Underestimating coverage needs happens when people rely solely on employer-provided insurance, which often leaves gaps.
“Life insurance is too expensive.” Many people overestimate costs. Term life insurance for a healthy 40-year-old can cost less than $30 per month for $500,000 in coverage. That’s often cheaper than your daily coffee habit.
“It’s too complicated to understand.” Life insurance doesn’t have to be complex. A simple term policy is straightforward: pay premiums, it pays out when you die. Done.
“I’m young and healthy, so I don’t need it yet.” This thinking gets dangerous fast. Life happens unexpectedly—accidents, illness, undiagnosed conditions. The younger and healthier you are, the cheaper your premiums. Waiting only costs you more money later.
“My family can figure it out without me.” Without clear financial protection, your family faces stress, potential debt, and tough decisions when they’re already grieving.
Life insurance isn’t about you—it’s about making sure your family can maintain their lifestyle and pursue their goals even when you’re not there to provide for them.
At Jenkins Insurance Agency, we help Sonoma families understand exactly what coverage makes sense for their unique situation. We explain what you’re buying, why you need it, and how it protects what matters most.
Pro tip: Calculate your actual financial needs by adding up your debts, expenses for 5-10 years, kids’ college goals, and funeral costs—then talk to a local agent about matching that number with the right policy.
Here’s a summary of common misconceptions and their financial impact on Sonoma families:
| Misconception | Why It’s Risky | Potential Family Impact |
|---|---|---|
| Employer coverage is enough | Usually ends if you leave job | Leaves coverage gaps for dependents |
| Life insurance is too expensive | Costs often overestimated | Misses affordable financial protection |
| Too complicated to understand | Simple policies available | May delay getting needed coverage |
| Young and healthy need none | Premiums rise with age | Misses low-cost opportunity |
| Family can manage without it | Underrates financial stress | Causes debt, loss of lifestyle |
Types of Life Insurance Policies Explained
Life insurance comes in two main flavors, and understanding the difference is crucial for choosing the right protection for your Sonoma family. Each type works differently, costs differently, and serves different financial goals. Let’s break down what you’re actually buying.
Term Life Insurance: Affordable Protection for a Set Period
Term life insurance covers a specified period with fixed or increasing premiums and pays benefits only if death occurs during that time. Think of it as “renting” protection for 10, 20, or 30 years.
Term policies are straightforward and budget-friendly. A healthy 35-year-old in Santa Rosa might pay $20-$40 monthly for $500,000 in 20-year coverage. You choose your term length, get a fixed premium, and if you die during that term, your family gets the full death benefit.
Here’s what makes term appealing:
- Lower monthly costs compared to permanent options
- Simple structure with no confusing riders or cash value components
- Perfect for specific goals like covering a mortgage or raising children
- Flexible terms from 10 to 40 years
- No savings component, so it’s pure protection
The trade-off: when your term ends, coverage stops. If you’re 65 and your 20-year term expires, you’re uninsured unless you buy a new policy (which costs more at your age).
Permanent Life Insurance: Lifelong Coverage with Cash Value
Permanent life insurance works differently. It covers you for your entire life, not just a set period. Permanent life insurance provides lifelong coverage with cash value accumulation, including whole, universal, and variable universal life policies.
Permanent policies build cash value over time—money you can borrow against or withdraw. This extra feature costs more upfront, but you’re getting more than just a death benefit.
Types of permanent insurance include:
- Whole life — fixed premiums, guaranteed cash value growth, most predictable
- Universal life (UL) — flexible premiums, variable cash value, more control
- Variable universal life (VUL) — you invest the cash value, higher risk and reward
Permanent policies make sense if you want lifetime protection and want to build cash savings alongside your death benefit. Many Sonoma families use them for estate planning or leaving behind wealth for heirs.
The right policy type depends on your timeline and goals—term protects your family through their most vulnerable years, while permanent ensures you’re covered no matter when you pass.
Comparing Term vs. Permanent at a Glance
| Factor | Term Life | Permanent Life |
|---|---|---|
| Coverage Length | Set period (10-40 years) | Your entire life |
| Monthly Cost | Lower | Higher |
| Cash Value | None | Yes, builds over time |
| Best For | Families with kids, mortgages | Long-term wealth, estates |
| Flexibility | Limited | More options and riders |
Most Sonoma families start with term life because it aligns with their biggest financial responsibilities. Kids need support for 18-20 years. Mortgages need covering. Term protects during those critical years at a price that fits the budget.
Pro tip: Start with term life to cover your immediate financial obligations, then add permanent life later if you want lifelong coverage and cash value growth—this layered approach gives you protection now and flexibility later.
How Life Insurance Secures Your Family
Life insurance isn’t abstract protection—it’s real money that lands in your family’s bank account when they need it most. That death benefit becomes their financial lifeline, allowing them to breathe while grieving and stay afloat during the hardest transition of their lives.
Here’s what that security actually looks like in practice.
Replacing Lost Income
Your paycheck does more than buy groceries. It pays the mortgage, covers utilities, funds kids’ activities, and keeps the household running. When you’re gone, life insurance provides a death benefit that replaces the insured’s income, covering expenses such as mortgage or rent and daily living costs.
Without that replacement income, your spouse might need to sell the house or move in with family. Your kids might lose extracurriculars. Financial stress piles on top of grief.
A properly sized life insurance policy prevents this. It gives your family breathing room to adjust, find employment if needed, and maintain stability without panic.
Covering Immediate and Ongoing Expenses
When someone dies, bills don’t pause. In fact, expenses spike immediately. Your family faces:
- Funeral and burial costs ($7,000–$15,000 in California)
- Medical bills from a final illness
- Outstanding debts like credit cards and car loans
- Property taxes and home maintenance
- Insurance premiums that continue
Life insurance helps ease the financial burden after death by providing funds that enable beneficiaries to maintain their lifestyle and address ongoing costs and obligations. Your death benefit pays these immediately, preventing your family from draining savings or going into debt.
Protecting Education and Future Goals
Many Sonoma parents worry about their kids’ futures. Life insurance ensures those dreams don’t disappear when you do.
Your death benefit can:
- Fund college educations without student loans burdening your kids
- Support trade school or vocational training
- Cover costs if a child has special needs
- Provide starter capital for adult children launching careers
Without life insurance, your kids might skip college entirely or graduate with crushing debt. With it, they have the same opportunities as if you’d lived.
Keeping the Family Home
For most Sonoma families, the house is the biggest financial obligation. A mortgage with 20–30 years remaining becomes impossible to pay without your income.
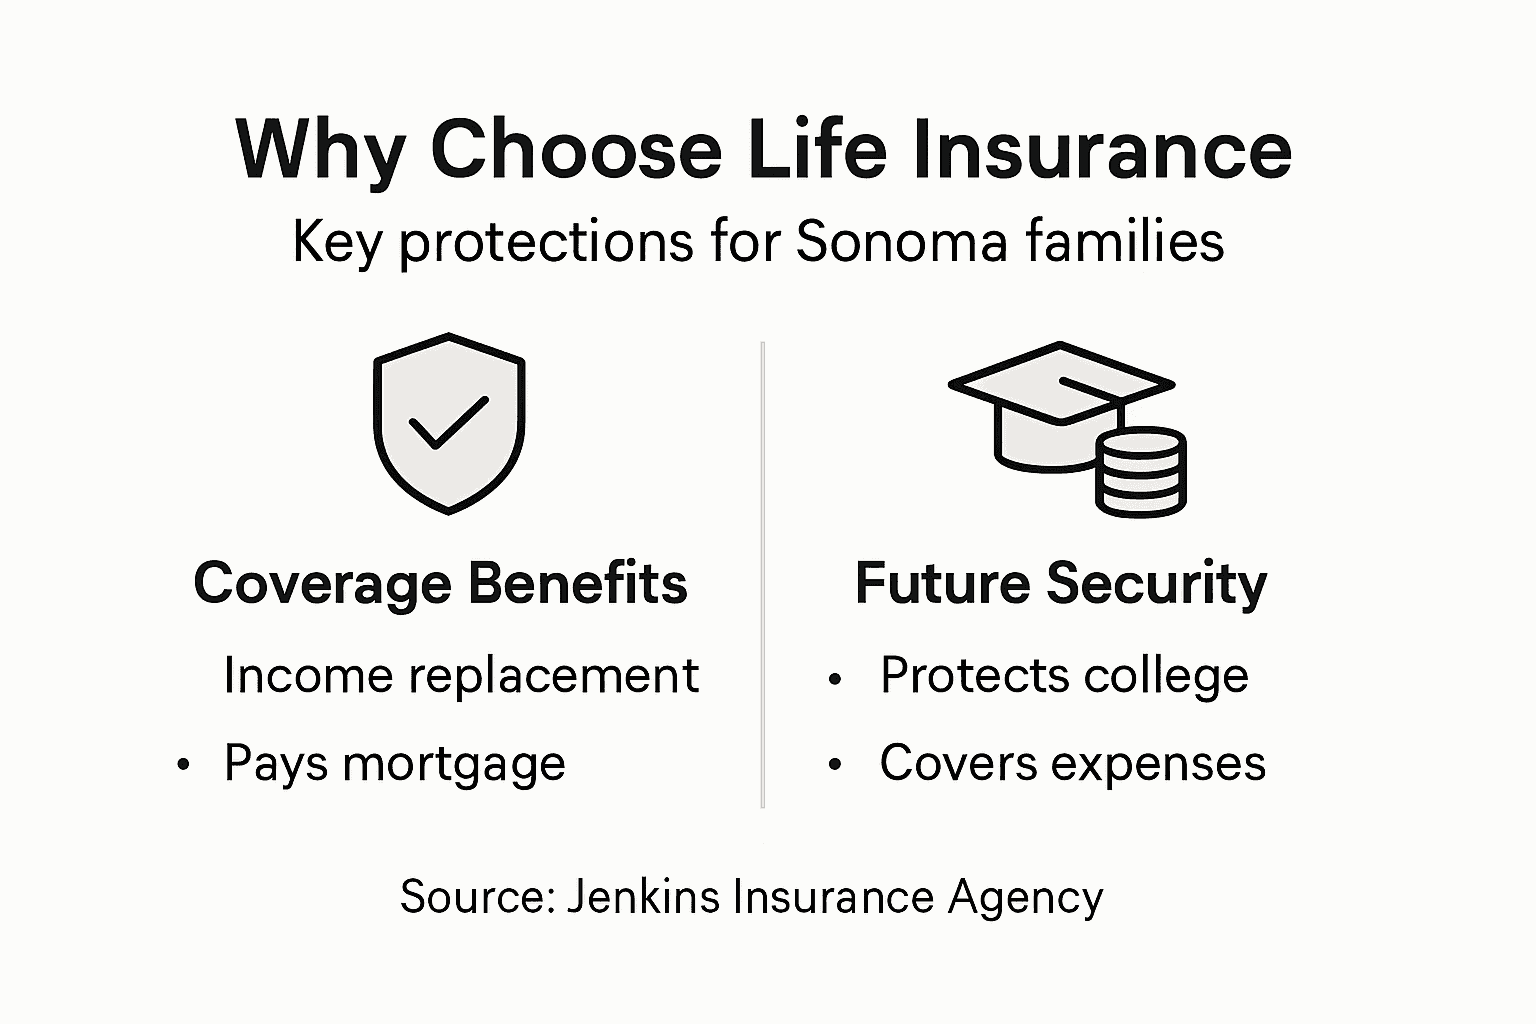
Life insurance covers the remaining mortgage balance, letting your family keep the home without the constant threat of foreclosure. Your kids stay in their schools. Your spouse doesn’t face the trauma of moving during grief.
Peace of Mind for Everyone
This is the invisible benefit nobody talks about. When you have life insurance, you sleep better. Your spouse knows the family won’t suffer financially. Your kids are protected. You’re not lying awake at 3 a.m. imagining worst-case scenarios.
Life insurance transforms “what if something happens to me?” from a terrifying nightmare into a manageable challenge your family can actually survive.
At Jenkins Insurance Agency, we help Sonoma families calculate exactly how much coverage they need. Not too little—which leaves gaps. Not too much—which wastes money. Just right for their unique situation.
Pro tip: Talk to your family about what they’d need if you weren’t here—kids’ education, mortgage payoff, living expenses for 10 years—then work with an agent to match those numbers with actual coverage.
Local Benefits for Sonoma County Residents
Choosing life insurance in Sonoma County means more than just buying a policy—it means working with people who understand your community’s unique challenges and resources. Local agents know what keeps Sonoma families up at night and how to address those specific concerns.
Here’s what makes getting life insurance in Sonoma different, and better.
Understanding Sonoma’s Economic Landscape
Sonoma County has a distinctive mix of urban, suburban, and rural communities. Housing costs in Santa Rosa differ from Healdsburg. Wine country employment is seasonal in ways other regions don’t experience. Cost of living fluctuates based on location within the county.
A local agent understands these nuances. They know that a vintner’s income looks different from a teacher’s. They recognize that some families face wildfire-related property risks that increase their overall financial vulnerability. They see how local economic trends affect your family’s long-term security needs.
National insurance companies use generic calculators. Local agents use local knowledge.
Access to Community Resources and Support Networks
When life insurance pays out, your family needs more than just money. They need community support. Sonoma County offers extensive resources that complement life insurance protection.
211 Sonoma County offers comprehensive resource and referral services connecting residents with local assistance, including help with healthcare, housing, emergency services, and financial support. Residents can access personalized assistance 24/7 by phone or text.
Your family can tap into:
- Mental health counseling during grief and adjustment
- Childcare assistance programs while parents work
- Food assistance and emergency financial aid
- Housing support if mortgage questions arise
- Legal aid for estate and financial matters
- Job training and employment services
These community safety nets work alongside your life insurance, creating a comprehensive protection system.
Working with Agents Who Know Your Neighborhood
Jenkins Insurance Agency operates from Santa Rosa but serves all of Sonoma County—Sebastopol, Guerneville, Ukiah, Cloverdale, and everywhere between. Our team understands local property values, income patterns, and regional risks that affect your coverage needs.
When you walk in, we’re not starting from zero. We ask about your specific situation: Do you own property subject to wildfire risk? Are you self-employed with variable income? Do you have aging parents in the county you’re supporting? Are your kids planning to attend local colleges?
These questions matter because they shape how much coverage you actually need.
Personalized Service That Reflects Community Values
Sonoma County values relationships over transactions. That’s not just sentiment—it’s how we operate. When you buy life insurance from a local agent, you’re establishing an ongoing relationship, not just completing a one-time purchase.
This means:
- Annual reviews as your family circumstances change
- Updates when you buy property, have children, or experience major life events
- Accessible support when beneficiaries need to file claims
- Local guidance through the entire insurance lifecycle
Life insurance purchased from a local agent becomes part of your family’s financial security plan, not just a policy gathering dust in a file.
At Jenkins Insurance Agency, we’re your neighbors helping you protect what matters most. We return your calls. We remember your kids’ names. We show up when you need us.
Pro tip: Schedule a complimentary consultation with a local agent to discuss your family’s specific needs—they can identify coverage gaps based on Sonoma County conditions that online quotes completely miss.
Financial Implications and Choosing the Right Policy
Life insurance isn’t just about emotional protection—it’s a financial decision that requires math, honesty, and strategic thinking. Getting it right means your family is truly protected. Getting it wrong wastes money or leaves gaps when you’re gone.
Let’s talk about the numbers and how to choose wisely.
Calculating Your Actual Coverage Needs
Determining the appropriate amount of life insurance requires evaluating financial obligations including mortgage, debts, income replacement, and future needs like education. This isn’t guesswork—it’s addition and subtraction.
Start by listing what your family would owe:
- Mortgage or rent (remaining balance or 5–10 years of payments)
- Car loans and credit card debt
- Student loans (yours or that you’d want paid off)
- Funeral and burial costs ($7,000–$15,000)
- Outstanding medical bills
Then add what they’d need going forward:
- Income replacement (5–10 years of your current salary)
- Kids’ college education ($50,000–$300,000 depending on schools)
- Childcare costs until kids are independent
- Property taxes and home maintenance
- Living expenses buffer for adjustment period
Add those numbers. That’s your baseline coverage need. Most Sonoma families need between $500,000 and $1.5 million.
Understanding Premium Costs and Affordability
Premiums depend on three things: your age, your health, and your policy type. You can’t change age, and health is mostly fixed, so policy type is your control lever.
Term life insurance usually offers the best value for most families, while permanent policies may offer additional features but at a higher price. A 40-year-old in good health pays roughly $30–$50 monthly for $500,000 in 20-year term coverage. The same person pays $200–$400 monthly for whole life.
Which is right? That depends on your timeline and budget.
Use this table to understand how age, health, and policy choice affect premiums:
| Factor | Effect on Premium | Example Outcome |
|---|---|---|
| Age | Older means higher premium | 40-year-old pays less than 60-year-old |
| Health | Better health lowers premium | No medical issues gets best rates |
| Policy Type | Term is cheapest, permanent costs more | $30/month for term; $200/month for whole life |
| Coverage Amount | Higher benefit costs more | $500,000 coverage cheaper than $1 million |
| Term Length | Longer terms raise costs | 30-year policy more expensive than 10-year |
Balancing Coverage Amount with Monthly Budget
The best policy is one you’ll actually keep and maintain. If premiums are too high, you might cancel it or skip payments. That defeats the purpose.
Here’s the strategic approach:
- Calculate your needs using the method above
- Get term quotes for that amount and various terms (10, 20, 30 years)
- Check affordability against your monthly budget
- If term is too expensive, reduce the benefit amount or extend the term length
- Add permanent life later once your finances stabilize
Starting with affordable term coverage beats having no coverage while you save up for the “perfect” permanent policy.
The Role of Professional Guidance
Consulting insurance professionals helps ensure the policy fits individual financial goals and commitments. This isn’t a solo project.
A local agent asks questions you might miss: Do you have dependents with special needs? Are you supporting aging parents? Do you own a business? Do you expect an inheritance? Each changes your coverage calculation.
They also explain policy details—surrender charges, conversion options, living benefits—that online calculators skip entirely.
The cheapest life insurance policy is worthless if it doesn’t actually cover your family’s real needs.
At Jenkins Insurance Agency, we work through these numbers with you. We show you options. We explain trade-offs. We help you choose coverage that protects your family without breaking the budget.
Pro tip: List your debts and expenses on paper, calculate your total need, then bring that number to an agent who can show you affordable options that actually work for your situation.
Secure Your Family’s Future with Trusted Life Insurance Solutions
The article highlights the real challenges Sonoma families face when protecting their loved ones financially after unexpected loss. It reveals common misunderstandings about life insurance affordability, coverage needs, and how policies actually work to support families through difficult times. If you want clarity on terms like death benefit, income replacement, and the difference between term and permanent life insurance, you need personalized guidance that fits your unique life situation.
At Jenkins Insurance Agency Inc., we specialize in helping Sonoma County residents move beyond confusion and uncertainty to choose life insurance that truly protects what matters most. We take the time to understand your financial goals and avoid coverage gaps. Our local roots in Santa Rosa mean we know the specific risks and needs of families in this community. Whether you want straightforward term coverage for your mortgage or a permanent policy for lifelong peace of mind, we offer honest advice and tailored options.
Explore how insurance can secure your family’s future by visiting our Uncategorized – Jenkins Insurance Agency Inc. page for insights or start with a complimentary consultation today.

Don’t leave your family’s financial security to chance or guesswork. Act now to get expert help in selecting life insurance that meets your needs without breaking your budget. Contact Jenkins Insurance Agency Inc. for compassionate, local support that protects your loved ones when it matters most.
Frequently Asked Questions
What is life insurance, and how does it work?
Life insurance is a contract where you pay regular premiums, and in return, the policy pays a death benefit to your beneficiaries upon your death. It helps replace lost income and covers financial obligations like funeral costs, housing, and education expenses.
What are the main types of life insurance?
The two main types of life insurance are term life insurance and permanent life insurance. Term life offers coverage for a specific period (e.g., 10, 20, or 30 years) and is generally more affordable. Permanent life insurance provides lifelong coverage and can accumulate cash value over time, but it typically comes with higher premiums.
How can I determine how much life insurance coverage I need?
To calculate your life insurance needs, add up your outstanding debts, such as your mortgage and loans, along with future financial obligations like children’s education costs, and living expenses for your family. A common recommendation is to aim for 5-10 times your annual income.
Why should I consider life insurance if I’m young and healthy?
Being young and healthy often means you can secure lower premiums, making it an ideal time to purchase life insurance. Life is unpredictable, and having coverage ensures that your loved ones are financially protected in case of unexpected events.
Recommended
- Life Insurance Explained: Secure Your Family’s Future – Jenkins Insurance Agency Inc.
- Back to School? Time to Check Your Life Insurance – Jenkins Insurance Agency Inc.
- Life Insurance – Jenkins Insurance Agency Inc.
- 7 Essential Auto Insurance Coverages for Californians – Jenkins Insurance Agency Inc.