
Running a business in Santa Rosa means facing daily risks that could disrupt your operation in an instant. Small business owners need more than luck—they need protection that covers property damage, lawsuits, and lost income from unforeseen closures. A Business Owner’s Policy (BOP) offers bundled coverage for general liability, property, and business interruption, making it a practical solution for owners looking to safeguard both their assets and their future.
Table of Contents
- What Is Business Owner Insurance Coverage?
- Core Types And Key Differences Explained
- How Business Insurance Protects Your Company
- Legal And Regulatory Needs In California
- Common Risks, Costs, And Pitfalls For Owners
Key Takeaways
| Point | Details |
|---|---|
| Comprehensive Coverage | Business Owner’s Policy (BOP) combines essential coverages like property, general liability, and business interruption into one cost-effective package for small businesses. |
| Gap Awareness | Understanding the specific types of risks your business faces is crucial to avoid underinsurance and ensuring adequate coverage for operational needs. |
| Legal Compliance | California has stringent insurance requirements, including mandatory Workers’ Compensation for businesses with employees, which must be closely adhered to. |
| Review and Update | Regularly review your policy to adjust coverage limits in line with business growth and changes in circumstances to mitigate financial risks effectively. |
What Is Business Owner Insurance Coverage?
Business owner insurance is specifically designed to protect your Santa Rosa business from the everyday risks that could shut you down. A Business Owner’s Policy (BOP) is essentially an insurance package that combines multiple coverages into one solution rather than forcing you to purchase separate policies.
Think of it as one comprehensive shield instead of three or four different ones. Instead of buying general liability, property coverage, and business interruption separately, a BOP puts them together in a cost-effective package tailored for small and medium-sized businesses like yours.
Core Coverage Components
Most business owner policies include these essential protections:
-
Property insurance covers your building (if you own it), equipment, inventory, and other business assets against fire, theft, vandalism, and weather damage.
-
General liability coverage protects you if someone gets injured on your property or if your business operations cause damage to someone else’s property. This also covers legal fees if you’re sued.
-
Business interruption insurance reimburses lost income when you’re forced to close temporarily due to a covered event like a fire. This is critical—it keeps you afloat during recovery.
These three pillars work together to address the most common threats to local Santa Rosa businesses. Without them, a single incident could devastate your operation.
What Makes It Different from Other Business Insurance
You might wonder how a BOP differs from buying policies individually. A BOP combines general liability and property insurance into a single affordable package specifically built for small business owners. The bundling saves you money compared to purchasing each policy separately.
A BOP isn’t designed for every type of business. If you operate a high-risk operation, professional services firm, or manufacturing facility, you may need specialized coverage beyond what a standard BOP offers. That’s where working with a local agent becomes invaluable—they understand your specific situation.
Coverage Variations You Should Know
Not all BOPs are identical. Most cover named perils (specific events like fire, theft, or storms). Some offer broader all-risk coverage that protects against almost any event except those specifically excluded in your policy.
Business interruption insurance, while often included, may have waiting periods before coverage kicks in. Some policies cover up to 30 days of lost income; others extend coverage longer. The details matter when an emergency hits.
A BOP is fundamentally designed to give small and medium-sized businesses affordable, bundled protection without gaps that could drain your savings.
Pro tip: Review your coverage limits annually—as your Santa Rosa business grows, your property value and liability exposure likely grow too, and your insurance should keep pace.
Core Types And Key Differences Explained
Business insurance comes in multiple flavors, and understanding the differences protects you from gaps in coverage. Not every business needs every type—your specific risks determine what you actually require. A Santa Rosa retail shop faces different threats than a consulting firm or construction company.
The Main Types of Business Insurance
The core types of business insurance include general liability, property, workers’ compensation, and professional liability. Each addresses different risk categories that could impact your bottom line.
-
General liability covers bodily injury claims and property damage lawsuits when someone is hurt or damaged property on your premises or due to your operations.
-
Commercial property insurance protects your physical assets—buildings, equipment, inventory, and fixtures—against fire, theft, vandalism, and weather events.
-
Workers’ compensation is required if you have employees and covers medical expenses and lost wages when a worker is injured on the job.
-
Professional liability protects service providers like consultants, accountants, and contractors against malpractice or negligence claims.
How a BOP Differs from Individual Policies
A Business Owner’s Policy bundles property, general liability, and business interruption into one package. You’re not buying these separately—they work together as a coordinated system.
When you purchase individual policies, you might accidentally create overlaps or miss coverage gaps. A BOP eliminates that confusion by bundling the coverages most small businesses actually need.
Here’s a quick comparison of individual policies versus a Business Owner’s Policy (BOP):
| Insurance Approach | Coverage Overlap Risk | Cost Efficiency | Policy Management Difficulty |
|---|---|---|---|
| Separate Policies | Higher, may miss gaps | More expensive | Complex, multiple documents |
| Business Owner’s Policy | Lower, bundled cover | More affordable overall | Simple, single policy |
Product and Professional Liability: When You Need Them
If you sell physical products, product liability insurance protects you when your product causes injury or damage. If someone gets hurt using your product and sues, this covers legal defense and damages.
Professional liability is different. If you provide services and a client claims you didn’t deliver properly or caused them financial loss through your work, this coverage steps in. Your accountant, lawyer, or contractor absolutely needs this.
Choosing What Your Santa Rosa Business Actually Needs
The gap between overinsuring and underinsuring can be costly either way. Overinsuring means wasted money on coverage you’ll never use. Underinsuring means a single incident could bankrupt you.
Your business type, employee count, revenue, and industry risk level all factor in. A home-based consulting business looks completely different from a retail storefront with equipment and customer foot traffic.
Bundled coverage through a BOP typically costs less than buying general liability, property insurance, and business interruption separately while providing streamlined protection.
Pro tip: Meet with a local agent to review your actual operations and inventory—they’ll identify specific risks unique to your Santa Rosa business that standard templates might miss.
How Business Insurance Protects Your Company
Business insurance is your financial safety net when unexpected events threaten your operations. Without it, a single lawsuit, property disaster, or employee injury could wipe out years of hard work and personal savings. Insurance steps in where your business structure alone cannot protect you.
Think of it as a buffer between your company’s risks and your personal finances. Your LLC or corporation provides some liability protection, but it doesn’t cover property damage, lawsuits, or lost income during closures. Insurance fills those critical gaps.
The Financial Protection Layer
Business insurance safeguards your company by protecting against financial consequences of unforeseen events. This includes coverage for legal fees, medical expenses, property damage, and lost income during interruptions.
Consider what happens when disaster strikes:
-
A customer slips in your store and sues for medical bills and lost wages—general liability covers this.
-
A fire destroys your equipment and inventory—property insurance replaces what you lost.
-
A pipe bursts and forces temporary closure—business interruption insurance covers your operating expenses while you rebuild.
-
You make a professional mistake that costs a client money—errors and omissions coverage handles the defense and settlement.
Without these protections, you’re personally responsible for these costs.
Protecting Both Your Assets and Your Livelihood
Business insurance protects two things: your company’s physical and financial assets, and your personal wealth. In Santa Rosa, where property values are significant and business competition is fierce, this distinction matters enormously.
Your building, equipment, inventory, vehicles, and cash reserves are all at risk without proper coverage. Insurance means these assets are replaced or repaired rather than lost forever.
Professional Mistakes and Service Liability
If you provide services, errors and omissions insurance protects against financial losses from professional mistakes or negligence. This covers legal defense costs, settlements, and judgments when clients claim you failed to deliver.
Consultants, contractors, accountants, and advisors absolutely need this. One billing error or missed deadline can trigger a lawsuit that drains your resources without this safety net.
Business Continuity When Disaster Hits
The worst part about a major incident isn’t always the immediate damage—it’s the inability to operate while you rebuild. Business interruption insurance ensures you can pay rent, payroll, and utilities during forced closures.
This keeps your business alive instead of forcing permanent closure when recovery is still possible.
Insurance transforms catastrophic financial risks into manageable, predictable costs that your business can absorb and recover from.
Pro tip: Document your business assets, equipment values, and annual revenue now—this inventory becomes invaluable when filing insurance claims after an incident.
Legal And Regulatory Needs In California
California doesn’t leave business insurance to chance. The state has strict requirements that vary by industry, company size, and how you operate. Ignoring these requirements can result in fines, license suspension, or legal liability that insurance won’t cover.
Santa Rosa business owners operate under California’s regulatory framework, which is more stringent than many other states. Understanding what you’re legally required to carry is the first step toward compliance and protection.
Mandatory Insurance in California
California businesses must comply with specific insurance requirements based on industry and size. The two most common mandates affect nearly every business operating in the state.
Workers’ Compensation is the big one. If you have even one employee, you must carry it. This covers medical treatment and wage replacement when workers are injured or become ill due to job duties. California enforces this requirement strictly—violations can result in penalties exceeding $10,000 per incident.
Commercial Auto Insurance is required if you use any vehicle for business purposes. This isn’t optional just because you use a personal car occasionally for business errands.
Vehicle and Liability Requirements
California law mandates minimum liability insurance for motor vehicles used in business, including coverage for injuries and property damage. The minimums are:
-
$15,000 for injury or death to one person
-
$30,000 for injury or death to multiple persons
-
$5,000 for property damage
These are floor amounts. If you cause a serious accident, these minimums won’t cover damages. Many Santa Rosa business owners carry higher limits for actual protection.
Industry-Specific Requirements
Certain industries face additional mandates. Contractors need specific licenses and insurance. Childcare facilities have strict requirements. Healthcare providers need professional liability coverage. Construction companies face different thresholds than retail shops.
Your specific industry determines what’s legally necessary versus what’s prudent additional protection. A contractor in Santa Rosa operates under different rules than an accounting firm.
To better understand which insurance types fit your business in Santa Rosa, see this summary:
| Business Type | Best Coverage Types | Major Risks Addressed |
|---|---|---|
| Retail Store | BOP, product liability | Theft, fire, customer injuries |
| Consulting Firm | BOP, professional liability | Negligence, data breaches |
| Construction Company | Workers’ comp, vehicle, BOP | Employee injury, equipment loss |
| Childcare Facility | BOP, professional liability | Regulatory, child safety |
The Compliance Reality
State regulators actively enforce these requirements. Operating without mandatory coverage isn’t just risky—it’s illegal. If an accident happens and you’re uninsured, you’re personally liable for all damages. An LLC or corporation won’t protect you if you knowingly violated insurance requirements.
The California Department of Insurance provides guidance, but requirements change and vary significantly by situation. This is why working with someone who understands California’s specific landscape matters.
Non-compliance with California insurance requirements can result in fines, license suspension, and personal liability that extends beyond your business structure.
Pro tip: Review your current coverage against California’s specific industry requirements annually—regulations change, and your business may have grown into new requirement categories since you last checked.
Common Risks, Costs, And Pitfalls For Owners
Running a business means facing risks you can’t always predict or control. Business owners face seven types of risks including strategic, compliance, financial, operational, and reputational threats. Each one can derail your Santa Rosa business if you’re unprepared, and costs escalate quickly when incidents occur.
Understanding what can go wrong—and what it costs when it does—helps you make smarter insurance decisions. Most business owners underestimate both the likelihood and financial impact of common disasters.
The Real Risks You Face Daily
You already know about fire and theft. But operational risks are sneakier. A customer slips and falls. An employee gets injured. A mistake in your work causes a client financial loss. A key supplier suddenly goes out of business. Market competition intensifies. Regulatory requirements change.
These aren’t theoretical scenarios. They happen to Santa Rosa business owners regularly.
The Hidden Cost of Underinsurance
One common pitfall is assuming a Business Owner’s Policy covers all risks when it actually has coverage limits and exclusions. A standard BOP might cover property damage up to $50,000, but if your inventory and equipment are worth $200,000, you’re severely underinsured.
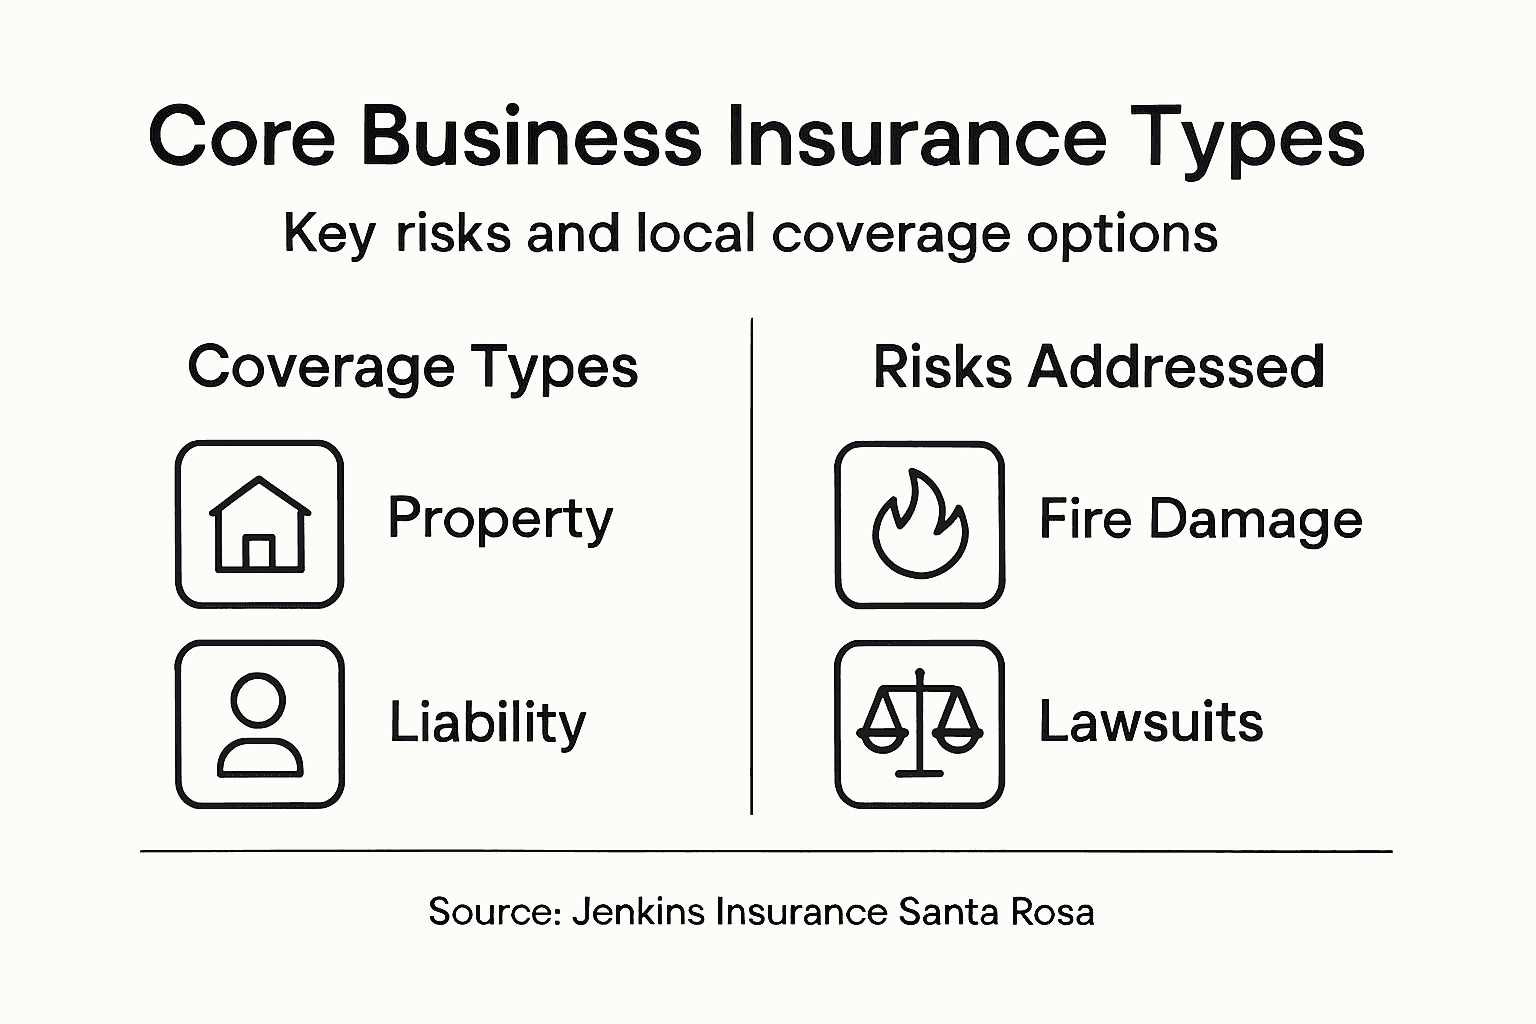
Costs vary dramatically by industry, location, and business size. A small retail shop in Santa Rosa pays different premiums than a construction contractor or professional services firm. What matters is matching coverage limits to your actual exposure.
Common Coverage Gaps
Business owners often discover too late that their policy doesn’t cover what they assumed:
-
Workers’ compensation isn’t bundled in basic BOPs—you must add it separately if you have employees.
-
Commercial vehicle insurance requires its own policy if you use vehicles for business.
-
Professional liability isn’t standard unless you specifically request it as a service provider.
-
Cyber insurance doesn’t come automatically, but data breaches can cost thousands in recovery and notification expenses.
-
Business interruption limits might cover only 30 days when your recovery takes 90 days.
Each gap represents potential financial disaster when incident claims arise.
Cost Considerations for Your Budget
Insurance costs are investments in protection, not pure expenses. A $100-per-month policy that prevents a $50,000 claim pays for itself 500 times over. The real question isn’t whether you can afford insurance—it’s whether you can afford not to have it.
Santa Rosa business owners often underestimate claim frequencies. Natural disasters, liability lawsuits, and employee injuries happen more often than most owners expect.
The costliest pitfall is misunderstanding policy terms, discovering gaps only when you need coverage and finding it doesn’t apply to your situation.
Pro tip: Request a comprehensive risk assessment from your insurance agent before settling on coverage limits—they’ll identify specific exposures unique to your Santa Rosa business that generic policies miss.
Protect Your Santa Rosa Business with Personalized Insurance Solutions
Facing the daily risks of running a business in Santa Rosa can feel overwhelming. Challenges like property damage, liability claims, and unexpected interruptions threaten not only your operations but also your financial stability. The article highlights the importance of understanding business owner insurance coverage and how a tailored Business Owner’s Policy (BOP) can shield your business from these critical vulnerabilities.
At Jenkins Insurance Agency Inc., we specialize in providing personalized business insurance solutions designed specifically for local entrepreneurs. With knowledge of California’s legal requirements and the unique risks Santa Rosa businesses encounter, we help you avoid costly coverage gaps and ensure your protection is both comprehensive and affordable. Don’t leave your livelihood to chance when expert, neighborly support is just a click away.
Explore how our dedicated team can build the right coverage for your business needs by visiting our Uncategorized – Jenkins Insurance Agency Inc. page.

Secure your business future today with trusted, local guidance. Contact Jenkins Insurance Agency Inc. at https://jenkinsinsuranceagencyinc.com and let us help you craft a custom plan that keeps your Santa Rosa business protected from unexpected dangers.
Frequently Asked Questions
What is a Business Owner’s Policy (BOP)?
A Business Owner’s Policy (BOP) is an insurance package that combines essential coverages like property insurance, general liability, and business interruption into one cost-effective solution tailored for small and medium-sized businesses.
What are the core coverage components of business owner insurance?
The core components typically include property insurance, which protects your physical assets; general liability coverage, which guards against claims of injury or property damage; and business interruption insurance, which compensates for lost income during unexpected closures due to covered events.
How does a BOP differ from individual business insurance policies?
A BOP bundles multiple coverages into one policy, making it more affordable and easier to manage compared to purchasing separate individual policies. This reduces the risk of overlap and coverage gaps that may occur with individual policies.
Why is it important to have business interruption insurance?
Business interruption insurance is crucial because it helps cover lost income and operating expenses when your business is temporarily closed due to unforeseen events like a fire or natural disaster, ensuring you can maintain financial stability during recovery.
Recommended
- The Top 7 Insurance Policies Every Small Business Owner Needs – Jenkins Insurance Agency Inc.
- 7 Essential Common Business Insurance Policies Explained – Jenkins Insurance Agency Inc.
- 7 Essential Business Property Insurance Types Explained – Jenkins Insurance Agency Inc.
- Business Insurance Benefits for Sonoma County Owners – Jenkins Insurance Agency Inc.